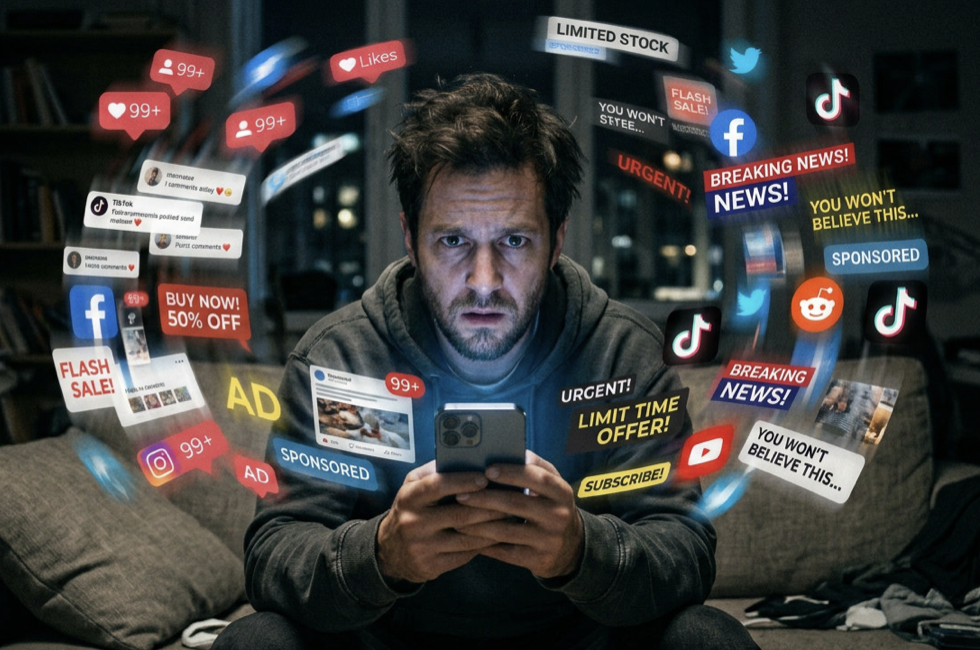
With a nearly infinite supply of content and ads available, but with the same number of hours in a day, the cost of capturing attention is increasing every year.
With feeds being flooded with functionally limitless AI-assisted content, consumer attention has become an even more scarce resource. Bill Sparks examines the forces that are eroding advertising’s fundamental economics.
The global advertising market is about to cross $1 trillion for the first time. Dentsu's December 2025 forecast put it on that trajectory, and Magna's June 2026 update confirmed it, projecting media-owner ad revenue of $979 billion in 2025 with 6.3% growth in 2026. By the top-line numbers, the industry has never been healthier.
So why is it getting harder to sell anything?
A Metricool study of more than 44,000 advertisers and $471 million in ad spend found that Meta's return on ad spend fell from $5.48 per dollar in 2025 to $4.57 in 2026. For the largest advertisers, those spending more than $10,000 a month, the drop was steeper: from $4.88 to $3.97. The World Advertising Research Center (WARC) cut its global ad-spend growth forecast by nearly $20 billion over two years, citing "mounting uncertainty." Magna revised its U.S. growth projection downward, from 4.9% to 4.3%.
The advertising market is not collapsing. It is inflating. Companies are spending more money to reach fewer people, less effectively, at higher cost. That is the attention recession: not a decline in ad dollars, but a decline in what those dollars buy.
Three forces eating the return
The deterioration has structural causes, not cyclical ones. Three forces are converging to erode advertising's fundamental economics, and none of them are going away.
The first is volume. AI-generated content has shattered the scarcity model that advertising depended on. Ads used to compete for attention against a finite supply of human-created content. That supply is now functionally infinite. A brand that spent $50,000 producing a product video in 2023 is now competing against AI-assisted content that costs a few dollars to generate and floods the same feed by the thousands. Feeds are denser, scroll times are longer, and the competition for any single second of a viewer's attention has intensified dramatically. Meta reported 34% more posts in its feed in late 2024 compared to 2022, with no corresponding increase in time spent. The content grew. The attention didn't. When content is limitless, attention becomes the scarce resource, and the cost of capturing a unit of it rises while the value of each impression falls.
The second is avoidance. Nearly 30% of internet users worldwide now use ad blockers, according to consumer intelligence platform GWI's Q2 2025 data, with the figure reaching 33% in the United States. The demographic skew matters more than the headline number: men aged 25 to 34 block at the highest rates, and usage is concentrated among younger, higher-income users. On mobile, the picture is worse. Flurry Analytics has tracked Apple's App Tracking Transparency opt-out rates since the feature launched, and the data is consistent: roughly three out of four iOS users decline tracking when prompted. The audience most valuable to advertisers is the audience most actively avoiding them.
The third is fragmentation. Audiences are now distributed across a dozen or more platforms, but most advertisers haven't adjusted. Metricool's 2026 study found that 91% of advertisers running campaigns on Meta and TikTok were running them only on Meta. Consumers have moved; budgets have not. The result is thinner coverage across more surfaces at higher cost per impression, with no single channel delivering the concentration of attention that made mass-market advertising efficient in the first place.
The Adidas confession
Adidas accidentally discovered its last-click attribution was being systematically overstated when an AdWords outage in Latin America didn’t result in a drop in sales. It turned out the digital performance channels had been riding on the brand's coat-tails.
None of this is theoretical. One of the world's largest advertisers already learned the lesson the hard way.
Simon Peel, Adidas's global media director, told the audience at EffWeek that the company had spent years over-investing in performance marketing at the expense of brand-building. The numbers were stark: 77% of Adidas's marketing budget went to performance channels and 23% to brand, almost exactly the inverse of the 60/40 brand-to-performance ratio that Les Binet and Peter Field's effectiveness research recommends. Adidas was chasing last-click attribution across four different models (Google Last Click, Google Custom, Adobe, and Facebook), and all four systematically overstated digital's contribution.
The proof came by accident. When an AdWords outage knocked out paid search in Latin America, Adidas's traffic and revenue didn't drop. Organic search was doing the work; paid search was taking the credit. When the company finally built econometric models, they found that video, television, outdoor, and cinema were the channels actually driving e-commerce sales. The digital performance channels claiming those conversions had been, in Peel's framing, riding on the brand's coat-tails.
Adidas is not an outlier. According to eMarketer data cited by Digiday in 2026, 36% of marketers worldwide now plan to increase brand marketing investment, up from 31% the year before. Direct-to-consumer brands like Parachute and Halara have publicly shifted spend toward experiential campaigns and brand-building activations. Polly Wong, president of direct marketing agency Belardi Wong, put the problem plainly: "If you only focus on bottom-funnel marketing for a couple of years, eventually it backfires on you."
What this means for marketing strategies
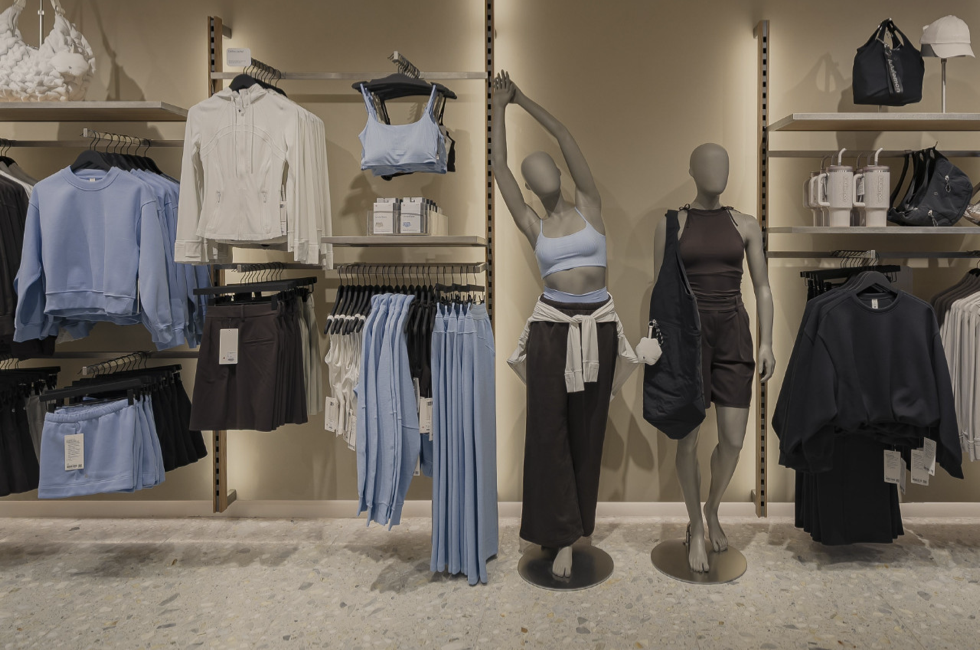
Lululemon grew to $9.6 billion in annual revenue with a marketing model built around local ambassador partnerships rather than the mass advertising its direct competitors depend on.
The attention recession does not require a radical overhaul of marketing strategy. It requires a more honest accounting of what advertising actually delivers today versus what it delivered five years ago.
Start with the math. Most organizations track CPM and cost per acquisition, but very few measure cost per unit of qualified attention, the metric that actually reflects what's changed. If your CPMs have doubled while your conversion rates have been cut in half, your effective cost of reaching a customer who acts has roughly quadrupled. That number rarely appears in a marketing dashboard, but it is the number that explains why spend keeps rising and results keep flattening.
Then look at where the money is going. If a significant share of your digital budget targets channels where a third of users block ads and three-quarters of mobile users have opted out of tracking, you are buying impressions that functionally do not exist. This is not a marginal inefficiency. It is a structural misallocation that compounds every quarter.
The companies pulling ahead in this environment are not necessarily spending less. They are spending differently, shifting dollars from rented attention on platforms they do not control toward owned relationships, earned authority, and experiences that people choose rather than tolerate. Lululemon grew to $9.6 billion in annual revenue with a marketing model built around local ambassador partnerships — yoga instructors, run-club leaders, personal trainers — rather than the mass advertising its direct competitors depend on. Duolingo reached 52.7 million daily active users while spending just 12% of revenue on sales and marketing, having built its audience largely through organic social content that people shared because it was genuinely entertaining, not because it was promoted. These are not edge cases from scrappy startups. EY’s 2026 media trends report identifies "the rise of experiences" as a dominant counter-trend, and brands across industries are increasing investment in physical activations, owned content, and direct audience relationships as a hedge against the declining returns of paid digital.
That transition is uncomfortable for organizations built around performance dashboards and last-click attribution. It means telling the board that the most measurable channel is not the most effective one, and that the line items easiest to justify on a spreadsheet are the ones delivering the least value per dollar. But the math is getting harder to argue with. And the companies that confront it honestly will be better positioned than those that keep buying more of what is delivering less.
Pfanner Advantage works with clients to turn change into advantage at the intersection of mobility, motorsport, media, technology, and marketing. Learn more or start a conversation: contact us today.
More Cold Read Insights from Bill Sparks:
When the Customer is a Machine
Should You Allow AI Bots to Crawl Your Site
How AI Is Getting Between Brands And Customers
America Is Building Cars The World Has Stopped Buying
What 1979 Tells Detroit About 2026
Why Aren’t Americans Buying EVs?
Part 8: State of the Art Branding Case Studies
Part 7: How the Ad Industry is Reinventing Itself
Part 6: AI and the Personalization of Brand Narrative
Part 5: Building Brand Loyalty Through Community
Part 4: Independent Creators as Brand Storytellers
Part 3: Brands as Publshers: The Rise of Owned Media
The Advantage Journal arrives every week. What matters in sport, mobility, media, and technology — curated and contextualized by Bill Sparks, Bill Long, and Paul Pfanner. No hedging. No filler. Subscribe — It’s Free